Get the number wrong and you will spend years living smaller than you had to, or run short at exactly the moment your options are fewest.
The brochure shows a couple on a beach. The budget beneath them assumes they will spend roughly twenty percent less than they did while working, occupy their paid-off home at minimal cost, and draw a tidy, predictable income until a round number of years is up. It is a clean picture. It is also, for most people, wrong from the first month.
Spending surges in the early years rather than easing. The paid-off home keeps sending bills. Adult children arrive as a recurring expense nobody named on the spreadsheet. And the act of drawing down a portfolio that took three decades to build feels, emotionally, like losing ground rather than living well.
The plan does not fail because the mathematics was wrong. It fails because it was assembled around a model of how a rational actor behaves, not how an actual person feels when the structure of working life disappears and the account balance starts moving in the wrong direction.
What follows names the specific psychological forces that quietly break retirement budgets, and gives you the honest questions any number on your plan must be able to survive.
Early Retirees Spend More, Not Less
The first years of retirement are the peak of discretionary spending, not the beginning of a gentle decline – and almost no retirement budget is built that way.
Financial planners have a term for this window: the go-go years. It describes the early stretch of retirement when health is good, mobility is high, and the appetite for experience is at its strongest. The problem is that most cautious budgets assumed this period would be the cheapest, not the most expensive.
The categories that drive the surge are recognisable and individually defensible: international travel that kept getting deferred, domestic trips to see family, dining out with the frequency that a working schedule never allowed, new hobbies that arrive with equipment costs and club memberships, and financial gifts to children who happen to need something right now. None of these feel like overspending. Each one feels like exactly what the money was saved for.
Collectively, they tend to run $10,000-$20,000 per year above the pre-retirement spending baseline. Across the first five years, that gap compounds to somewhere between $50,000 and $100,000 that the original plan never built a line for.
That is the specific trap. The surge doesn’t arrive wearing the face of a mistake – it arrives wearing the face of success, which is precisely why nobody plans for it. A budget that assumes retirement spending mirrors working-life spending, minus a few line items that disappear, will be wrong from the first month, and the shortfall will feel entirely justified the whole time.
⚠️ COMMON MISTAKE
The 'Go-Go Years' Cost More Than the Rest
Most plans assume spending stays flat or declines at retirement. The opposite is true for the first three to five years. Build a separate, higher line item for early retirement — and treat it as a certainty, not a worst case.
The 80% Replacement Rule Was Made Up
That benchmark has a birthplace, and it is a sales meeting. The figure emerged not from longitudinal data on how retirees actually spend but from a convenient subtraction: take working-life income, remove savings contributions and commuting costs, and the remainder is close to 80%. Easy to say, easy to remember, easy for a client to accept without questions.
The problem is that a retirement lasting 25 years does not have a single spending profile. The early window – when travel, dining, and new hobbies are running $10,000-$20,000 above the old baseline – may require 110 to 120 percent of pre-retirement income, not 80. A decade and a half later, when mobility has narrowed and the calendar is quieter, spending can genuinely drop to 60 percent. The single percentage papers over both ends of that curve.
It also papers over the middle: healthcare costs that rise steadily through the fifties and sixties of life, and the long-term or end-of-life care expenses that cluster in the final years and dwarf almost every other category. These are not edge cases. They are predictable phases of a long retirement, and the 80% figure was never designed to capture any of them.
The rule persists because a decade-by-decade spending model is harder to explain across a conference table – and harder for a client to nod along with – than a single round number. That is a reason for the rule’s survival, not a defence of its accuracy.
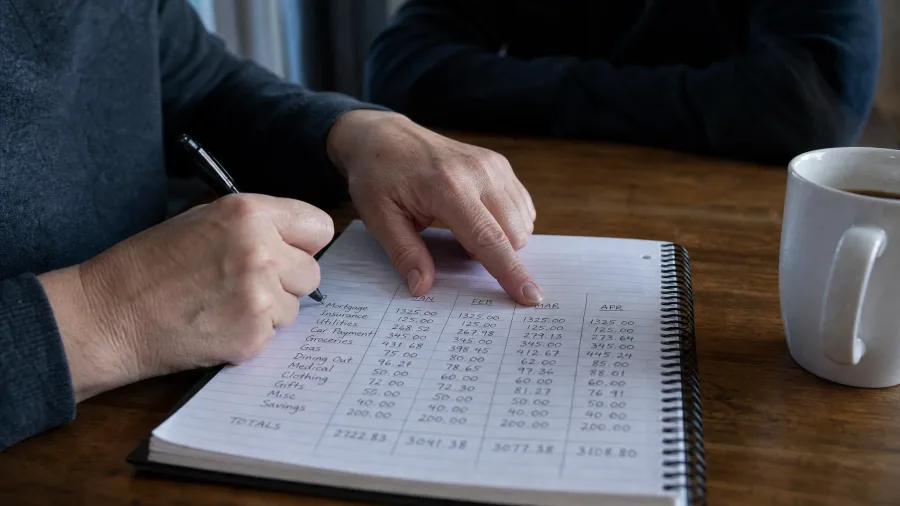
The corrective is less elegant but far more useful: track actual spending, category by category, for the two to three years before retirement. Not estimated spending – what is actually leaving the account each month and why. A number built from that record describes a real life, not a statistical average of someone else’s.
What the 80% Rule Quietly Erases
Longevity Adds a Decade Nobody Budgets For
Even a precise, category-by-category spending model still rests on a variable it cannot solve alone: how many years the money has to last. Most retirement tools quietly embed an answer to that question – and most of those answers are a generation out of date.
A 65-year-old planning today is looking at a horizon that commonly clears 20 years, and in a couple, the longer-lived partner frequently exceeds that. The tables baked into standard planning software were anchored to mortality data that predates decades of improvement in cardiovascular medicine and cancer survival. The tool looks authoritative; the assumption underneath it is stale.
That uncertainty creates a specific psychological trap. Faced with a horizon that might run 15 years or might run 30, many retirees resolve the anxiety by spending as little as possible in the early years – sitting on capital they were healthy enough to use, skipping the trip, declining the help, postponing the experience. The fear of the long end of the range quietly consumes the good end.
Running short of money in the final years is a genuine crisis. Dying with far more than was ever touched is a quieter failure – years of unnecessary constraint, bought with unnecessary caution.
The round numbers most people use – plan to 85, plan to 90 – carry a false confidence. They feel like decisions when they are really guesses. The SSA life expectancy calculator at ssa.gov produces a personalised figure based on actual birthdate and sex; it takes two minutes and gives a real starting point instead of a round number someone else chose. Every other variable in the plan should follow from that number, not from a default no one consciously set.
Pre-Medicare Healthcare Is a Budget Shock
Of all the numbers that shift when a longevity horizon stretches past twenty years, the one most people forget to price before they hand in their notice is private health insurance for every month that falls between their last day of work and their first day of Medicare coverage.
A couple leaving employment at 62 faces up to three years of that gap. Marketplace premiums in that age bracket – before any subsidy – typically land somewhere between $1,500 and $2,200 per month for the two of them; the exact figure changes year to year, so healthcare.gov is the only reliable place to verify what applies right now. At the middle of that range, the annual bill sits around $21,000. That is before a single deductible is met, before a co-pay, before any out-of-pocket cost from an actual health event.
Twenty-one thousand dollars is larger than most couples spend on food in a year.
What makes this cost psychologically different from, say, a travel budget that can be trimmed is that it is fixed, non-negotiable, and open-ended. It arrives every month regardless of what else the budget is doing, and there is no lever to pull when a tight month arrives. That specific combination – large, mandatory, indefinite – produces a quiet, persistent financial dread that is different in character from ordinary budget pressure. It does not spike; it sits.
The cost reshapes the retirement-date decision in ways that rarely get examined honestly. Many people who could retire at 62 by the numbers stay employed until 65 purely to avoid this gap, and the opportunity cost of those three extra working years – the go-go time spent at a desk – seldom appears anywhere in the analysis. Subsidies under current law can reduce the premium substantially, but eligibility depends on projected retirement income, which depends on withdrawal strategy, and most planning conversations never close that loop before the decision is made.
Pre-Medicare Healthcare — At a Glance
💰 Maximum gap length (retire at 62)
36 months before Medicare
📅 Total premium exposure at midpoint (36 months)
~$63,000 — before any claims
⚠️ What the premium does NOT cover
Deductibles, co-pays, out-of-pocket maximums — budget separately
🔍 When to verify subsidy eligibility
Before finalising withdrawal strategy, not after — amounts change annually at healthcare.gov
🗓️ The hidden trade-off
Staying employed to 65 avoids the gap but spends the highest-energy retirement years at a desk
The loop most plans never close
Subsidy size depends on retirement income. Retirement income depends on how much you withdraw. How much you withdraw depends on subsidy size. Settle the withdrawal strategy first — then check healthcare.gov with that number in hand.
The Paid-Off Home Still Costs Real Money
Owning a home outright removes the mortgage payment – it does not remove the bill.
The standard maintenance estimate runs 1-2% of home value per year. On a home worth $500,000-$600,000, that is $5,000-$12,000 annually, whether the mortgage is gone or not. Property taxes, homeowner’s insurance, and utility costs sit on top of that figure. None of them care that the deed is clear.
The timing problem is what makes older homes particularly punishing. A roof, an HVAC system, and original plumbing installed during the same renovation era all age on the same schedule. They do not fail in a tidy sequence spread across twenty years – they cluster. A retiree who faces a $12,000 roof replacement, a failing furnace, and a plumbing repair in the same two-year window is not unlucky. They are experiencing the predictable consequence of systems that were new at the same time.
Postponing repairs is the instinctive response when income no longer grows. Each bill feels too large against a fixed monthly draw, so the decision gets deferred. That pattern converts a $3,000 repair into a $9,000 structural fix – a well-documented dynamic that costs retirees multiples of what earlier action would have.
The harder question is the one the plan never asks: whether staying in the home makes financial sense at all. Many retirees remain in a house that consumes maintenance dollars, carries rising property taxes, and leaves most of its square footage empty – not because the numbers work, but because the home holds memory and identity that a spreadsheet cannot capture. That is a legitimate reason. It just needs to be a conscious one, with the actual carrying costs written down, not assumed away.
Adult Children Become a Recurring Line Item
Adult children rarely appear as a line item in a retirement plan, but they reliably become one.
The transfers take different shapes: a contribution toward a downpayment, an emergency loan extended during a job loss, school fees or childcare costs for a grandchild, co-signing a lease or a car loan that creates real contingent liability. Each one arrives as a singular event with its own justification. Taken together across a decade, they form a category – one that for middle-income families commonly totals $50,000-$150,000, and that at the upper end of that range rivals a substantial share of what a couple had set aside for their own discretionary spending.
The pressure to say yes is not weakness. It is parental identity responding to a child’s visible need. During working years, a regular salary absorbed these decisions without forcing a ledger entry – the money came in, the help went out, and the budget bent without breaking. In retirement, the same instinct operates against a fixed pool that does not replenish.
Given, not lost.
That distinction matters for planning. A market decline can be recovered from. Money transferred to an adult child generally cannot be clawed back – and the emotional weight of asking for it to be repaid typically ensures it will not be. In practice, the line between gift and loan collapses within a year or two of the original transfer, regardless of what was said at the time. A retirement budget that counts on repayment is a budget built on a fiction. The only figure that belongs in the plan is the amount you would give outright – and that number, written down honestly, is usually larger than the one most people are prepared to name.
💡 PRO TIP
Budget Gifts as Spent, Not Loaned
Any transfer to an adult child that you mentally label 'a loan' should go into the plan as a permanent outflow. The expectation of repayment is the part that damages the relationship and the budget simultaneously — and the repayment almost never arrives on schedule.
Spending Savings Feels Like Losing, Not Living
The anxiety of spending money you saved for exactly this purpose is not irrational – it is the predictable result of how a disciplined saver’s mind categorises money. Researchers who study financial decision-making consistently find that losses register with roughly twice the psychological force of equivalent gains. That asymmetry is well-documented in ordinary spending, but it hits with particular intensity when the money being spent is mentally filed as principal rather than income or interest.
Principal carries a different status in the saver’s mind. It is not the same as interest earned or dividends received – those feel like surplus, available to spend. Principal feels like the thing itself, the number that must not shrink. Spending it triggers something closer to the feeling of losing money than using it, even when drawing it down is the entire point of having saved it.
The cost is concrete. The go-go years – the early window of full health, energy, and appetite for experience – pass while the portfolio sits intact. Help that would make daily life easier gets refused. Investment income is used; the larger fund underneath it is not. Eventually that fund transfers to heirs who were not in the room when it was built.
The paradox is sharpest for the most disciplined savers. The same psychological habit that built a substantial fund – the refusal to touch capital, the instinct to preserve rather than consume – becomes the mechanism that prevents the fund from ever doing its job. A financial success turns into a behavioural failure.
Logic does not fix this. Knowing that drawdown is rational does not make it feel rational. What tends to work instead is restructuring the decision: relabelling the drawdown portion as something other than ‘principal’, or committing in advance to a scheduled withdrawal rate so each spending decision does not require a fresh act of will. The feeling will not change; the architecture around it can.
Breaking the Principal-Hoarding Cycle
Market Drops Hit Harder When You Are Withdrawing
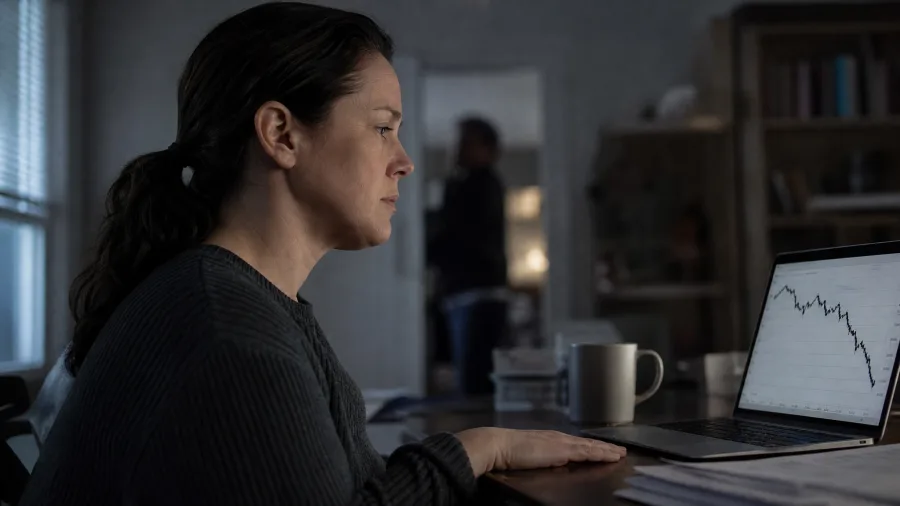
A portfolio decline during the withdrawal years lands differently than the same decline did during the saving years – and not just emotionally. The mathematics actually changed. When you were accumulating, a drop meant cheaper shares and time ahead to recover. When you are withdrawing, each monthly draw sells shares at the depressed price, which means fewer shares remain to participate in the recovery. The same percentage loss, at a different point in time, produces a structurally worse outcome.
Researchers who model this call it sequence-of-returns risk. A retiree who faces significant losses in years one through five, while simultaneously drawing down the portfolio, can exhaust funds years earlier than a retiree who experienced identical average returns but suffered those losses later. The brochure’s projected return says nothing about when the bad years arrive.
The primary threat is not the decline itself.
It is the panic sale – liquidating equities while prices are low and locking in a loss that would otherwise have been temporary. A portfolio that drops 25% and is held will likely recover. A portfolio that drops 25% and is sold to cash does not. The behavioural response to the decline is where the permanent damage happens, not the decline.
A cash reserve held outside the investment portfolio – enough to cover one to two years of spending – reduces the pressure that produces that response. If a short-term drop does not force an immediate withdrawal decision, the emotional urgency to act drops significantly. The right size of that buffer is personal; what matters is that it exists before the first bad quarter, not after.
Feeling this differently now than you did for three decades of accumulation is not a sign of irrationality. The stakes of each percentage point genuinely shifted the day withdrawals began. A plan that treats that shift as a weakness to be overcome, rather than a real change in circumstance to be designed around, will underperform the one that accounts for it.
Same 25% Drop, Two Different Structural Outcomes
During Accumulation
- Depressed price = more shares per contribution dollar
- A 25% drop needs a 33% gain to recover — and you have decades
- Next paycheck buys in at the lower price automatically
- Portfolio size is not the number you are living off yet
- Sequence of returns is irrelevant: average is what matters
During Drawdown
- Depressed price = more shares sold per withdrawal dollar
- A 25% drop still needs a 33% gain — but fewer shares remain to make it
- No new contributions to buy back in at the lower price
- Sequence of returns is now everything: early bad years cause lasting damage
- A 1–2 year cash buffer is the structural fix — held before the drop, not after
Identity Loss Shows Up Directly in the Budget
That market anxiety runs hotter when retirement still feels formless – and that formlessness has a budget of its own.
A working life quietly delivers four things that have nothing to do with salary: a reason to be somewhere by a specific time, a legible role in a hierarchy that others recognise, daily conversation with a fixed community, and the low-level sense that hours spent are producing something that counts. The paycheck gets replaced. Those four things do not.
When they disappear, spending fills the gap. A $400 pottery class that lasts six weeks. A club membership that costs $1,200 a year and gets used twice. A volunteer commitment that turns out to require its own equipment budget. A self-improvement trip framed as ‘finally doing something meaningful’ rather than as the leisure it actually is. Each purchase is individually reasonable. Together they are a category the original plan left blank.
The distinction that separates expensive from wasteful is not the dollar amount – it is whether the spending is buying into an identity that has been thought through, or just filling the discomfort of an unstructured Tuesday afternoon. Displacement spending does not deliver the satisfaction it promised, so it repeats.
The first two years carry the highest risk. The old identity has been handed in and the replacement has not taken shape yet, which means this is also the window where the money is most likely to go toward experiments that do not stick. This is a planning problem that shows up in the budget, but it starts in the question of what retirement is actually for.
🧭 The Identity Transition Arc in Early Retirement
Month 1–3: Honeymoon
Freedom feels total; spending on travel and experiences surges before any new structure forms.
Month 4–9: Disorientation
The absence of daily structure surfaces as restlessness, and displacement spending accelerates to fill it.
Month 10–18: Experimentation
New hobbies, courses, and memberships are trialled — most at cost, few retained long-term.
Year 2: Consolidation
A stable retirement identity begins to form around two or three activities with real roots.
Year 3+: Purposeful Spending
Spending aligns more closely with the identity that has solidified; displacement costs fall noticeably.
Couples Collide When Work’s Structure Disappears
That identity renegotiation rarely happens in isolation. When two people lose their separate work structures at the same time and suddenly share every waking hour, the financial friction that follows is usually the most visible symptom of something deeper.
For years, different money scripts coexisted because separate schedules and separate incomes contained them. One partner booked the weekend trip without much deliberation; the other winced but said nothing, because the cost came out of their own flow and the damage felt limited. That truce ends in retirement. The same joint account now funds everything both of them want to be, and the gap between their instincts about money stops being theoretical.
The fights that emerge sound like arguments about a restaurant bill or a home renovation quote. They are rarely about either. One partner is spending freely from a pool the other experiences as finite and irreplaceable. One has a retirement identity that requires expensive exploration – classes, travel, a sailboat – while the other is in a mode that feels, from the inside, like prudence, and feels, from the outside, like hoarding. Control and autonomy, which were once satisfied by separate titles and separate paycheques, now compete for a single shared calendar and a single shared balance.
Most joint retirement plans were built as one financial model. They were never negotiated as two psychological documents. Sitting down in the first year of retirement – not because something has gone wrong, but because misalignment is predictable – and naming each person’s actual spending instincts, separately and honestly, is the one intervention that addresses what the spreadsheet cannot see.
Frequently Asked Questions
How do I calculate how much income I actually need in retirement?
Track your real discretionary spending category by category for the two to three years before you retire — not what you think you spend, but what the bank statements show. Add a separate early-retirement line for travel, hobbies, and dining that reflects the go-go surge, and a separate healthcare line based on current healthcare.gov figures for your age. The 80% rule is a starting point for a conversation, not a final number.
What is sequence-of-returns risk and how does it affect me?
It is the mathematical reality that losses occurring early in retirement, combined with ongoing withdrawals, deplete a portfolio far faster than the same losses mid-accumulation would. The fix is not to avoid equities entirely but to hold a cash buffer outside the portfolio — typically 12 to 24 months of expenses — so a market decline does not force you to sell at depressed prices to fund normal spending.
How long should I plan for my retirement to last?
Do not use a round number like ’85’ or ’90’. Use the Social Security Administration life expectancy calculator at ssa.gov, which generates a figure based on your actual birthdate and gender. For couples, plan to the longer of the two horizons — the partner who outlives the other will bear the full budget alone. Most tools underestimate this by five to ten years, which is where longevity risk becomes real.
Why do I feel so anxious spending money I saved for retirement?
The feeling has a name: loss aversion applied to a mental account you labelled ‘principal’. Money mentally categorised as savings triggers a loss signal when spent, even when spending it is the entire purpose. The intervention that tends to work is pre-committing to a drawdown schedule before the year starts, removing the decision from each individual spending moment and replacing felt loss with planned income.
What should I budget for health insurance before Medicare?
For a couple aged 62–65, private insurance premiums currently run roughly $1,500–$2,200 per month before any subsidies. At the midpoint, that is approximately $21,000 per year in premiums alone, before deductibles or out-of-pocket costs. Check healthcare.gov for current figures and subsidy eligibility based on your projected retirement income — both change annually and the subsidy calculation depends heavily on how you structure withdrawals.
How do I talk to my partner about different money values before we retire?
The conversation works best when it is framed as two separate psychological documents that need to merge, not one joint spreadsheet to be divided. Each partner answers three questions independently: What does a typical month look like? What does money feel like when it is being spent from savings rather than earned? What would feel like too little, and what would feel like enough? Then compare the answers, not the numbers.
The Four Questions to Answer Before You Sign Any Number
Before you sign off on any retirement number, four questions need a truthful answer, not an optimistic one. When you imagine spending principal rather than interest or dividends, does it feel like living or like losing, and has your plan been built around that feeling rather than just the arithmetic? Who are you when you are not your job title, and is that identity specific enough to spend on purposefully rather than filling the hours at random? How much money will you actually give your adult children across the next decade, named as a line item and treated as a gift, not a loan you expect back? And does your partner hold a different money script than you do, because if the answer is yes and you have not had the explicit conversation about what shared daily life on a fixed portfolio will require from both of you, the spreadsheet is combining two different plans and calling it one.
The brochure couple on the beach is not a lie. But the budget underneath them belongs to someone who feels nothing when spending principal, never helps a child, maintains a home for free, and steps into retirement with a fully formed sense of purpose ready on day one.
You are not that person. You are someone with a specific partner, a specific home, specific children, and a specific psychological relationship to money that took decades to build and will not dissolve because a plan assumes it has. The version of the plan that holds is the one built around who you actually are. Start with those four questions, write the honest answers down, and then look at the number you signed.
Use the Tools Named in This Article
Run your personalised life-expectancy figure at ssa.gov, check your healthcare subsidy eligibility at healthcare.gov, and review current withdrawal guidance at irs.gov before finalising any retirement income number.