Most people assume that financial peace at seventy is simply the result of earning a massive salary for forty straight years.
That is rarely how it works in reality, because income and calm do not automatically live in the same house. When you are thirty-five, seventy feels like a distant country where everyone speaks a different language.
What you actually need to understand right now is how small financial friction compounds quietly over decades, shaping your daily choices long before retirement ever appears on the horizon.
Quick Tips Before You Start
Audit Daily Costs
Track every small subscription for one full month.
Automate Savings
Move cash into savings the exact day pay arrives.
Build a Buffer
Keep three months of strict living costs untouched.
1. Why Does Lifestyle Creep Cost You So Much Later?
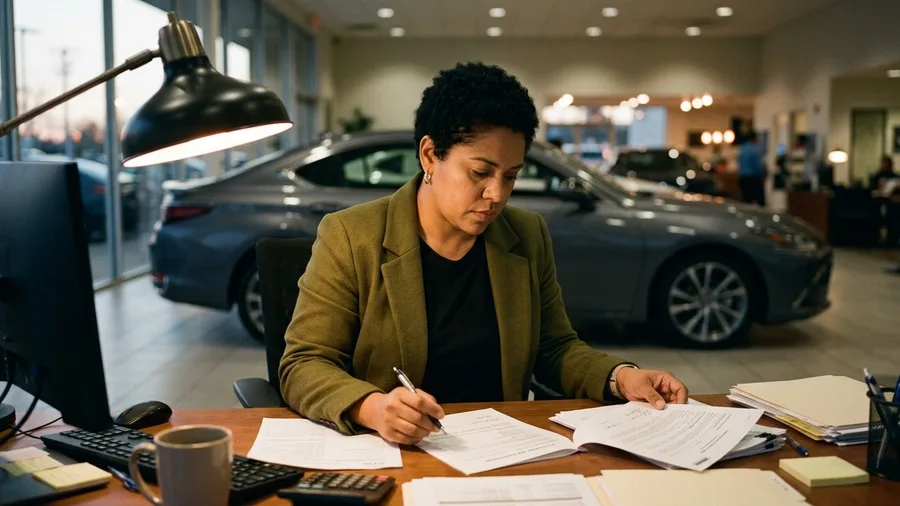
You sit at the dealership desk, sliding your pen across the finance agreement for a sleek new sedan, telling yourself that after three years of grinding sixty-hour work weeks, you have finally earned a smooth ride that does not rattle on the highway.
The monthly payment fits inside your recent promotion raise, so it feels like a harmless reward rather than a trap, but three years from now that car payment will still be draining cash from your checking account long after the dopamine of the new leather smell has faded completely.
This is how lifestyle creep operates in plain sight, swallowing every single financial gain you make before your bank balance ever has a chance to reflect your hard work.
You get a raise, and suddenly the morning coffee becomes an imported roast and the mid-size car becomes a luxury lease, happening so gradually that you never notice the shift in your baseline.
Every upgrade feels justified by hard work, but each one permanently raises your cost of living and extends the distance to genuine independence, trading freedom for temporary status.
What you are actually buying with that extra salary is not comfort; you are buying future obligations that tie you to your desk for another five years while quietly eroding your margin for error.
The real fix is keeping your living expenses flat for twelve months after every income bump, banking the difference before your lifestyle expands to swallow it whole.
⚠️ COMMON MISTAKE
The Raise Trap
Treating every promotion as a license to spend more guarantees you will work longer than you want to.
2. How Do You Stop Treating Savings Like an Afterthought?
Twelve times a year you wait for the end of the month to sweep up whatever loose change remains in your checking account. That money is already gone before you even look at it.
Treating savings as the final item on a checklist means you are betting against human nature every single cycle. There will always be a repair, a dinner out, or an unexpected bill waiting to absorb that exact residue.
Flip the sequence entirely and watch how the math shifts. Move money into a separate account the morning your paycheck hits, and learn to live on the remainder that was always yours to manage.
Best For
3. Is It Ever Actually Smart to Keep Cash Idle?
Is every single dollar outside of an active investment a mistake?
Keeping too much cash under a mattress or in a zero-yield checking account feels safe, but inflation eats its purchasing power every single month. You need emergency liquidity, but beyond that, idle cash is working against your future self.
The exception is money earmarked for a specific purchase within the next twelve months, where market drops would ruin your timeline. If the cash has a job with a date on it, let it sit.
At a Glance
4. What Words Should You Use When Declining Expensive Outings?
Conventional wisdom suggests that declining a costly social invitation requires a convincing, elaborate excuse to preserve your standing and keep the peace among friends.
You hesitate before declining a costly group dinner because you worry about how it will sound to your peers, eventually inventing a complex backstory about schedule conflicts that only adds awkward layers to a simple boundary.
What usually follows that elaborate performance is unnecessary internal anxiety and a noticeable dent in your monthly budget that takes weeks to recover from, all to avoid a moment of temporary discomfort.
Instead, try sending a direct, unvarnished text like I am keeping my dining budget tight this month, but let us grab coffee at the park instead, and then let the silence sit without apologizing for your financial priorities.
💡 Tip: Keep your financial boundaries brief and offer a low-cost alternative immediately.
Monthly Dining vs. Coffee Budget
5. Why Do Small Subscriptions Drain Your Net Worth?
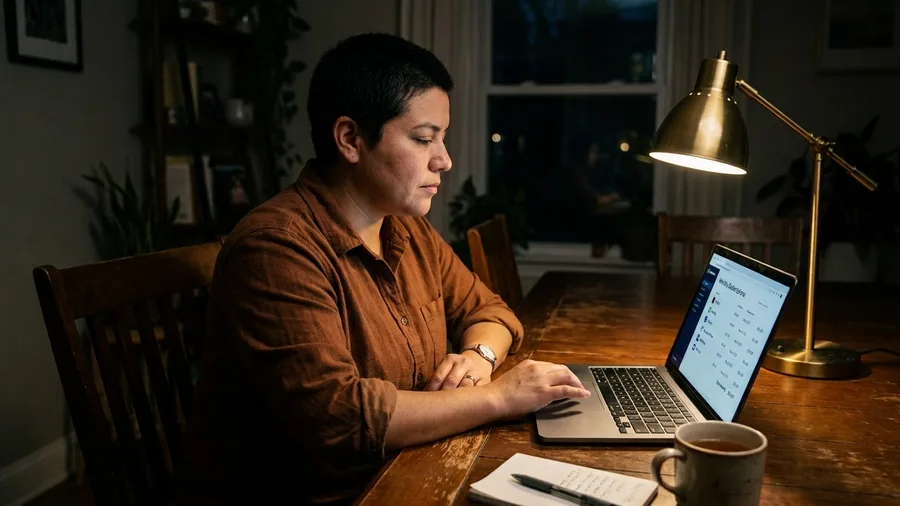
A steady leak in your checking account will sink a ship just as fast as a hole in the hull.
A dozen twelve-dollar charges slip past your notice every month because they are automatically billed to your card.
Individually they look harmless, but collectively they outpace a major utility bill over the course of a year.
Audit your statements every ninety days and cancel anything you have not used in the past thirty.
📈 Decades of Financial Clarity
Automate
Set up recurring transfers to savings the day you get paid.
Audit
Review and prune all monthly subscriptions every ninety days.
Invest
Keep index funds running smoothly without reacting to short-term noise.
Simplify
Focus your spending on experiences and durable goods that last.
6. How Does Impatience Destroy Decades of Compound Growth?
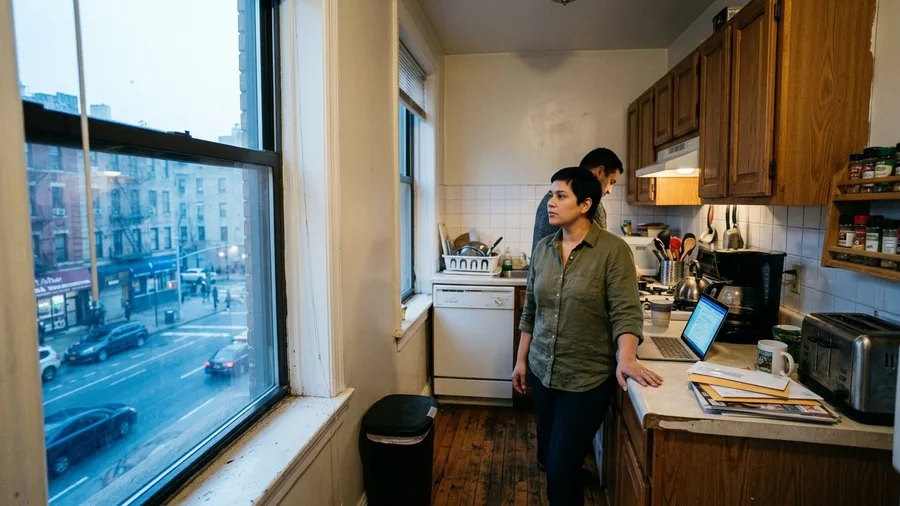
“We need to sell everything right now before it all goes to zero,” you tell your partner from the edge of the kitchen counter at seven in the morning while the coffee maker sputters its final drops into the glass carafe.
The laptop screen glows with a portfolio balance that has dipped four percent over the course of a single chaotic week, and the morning news anchors are screaming about an impending financial collapse from every corner of the screen.
What feels like a brilliant move to protect your hard-earned wealth is actually locking in permanent, irreversible losses at the absolute worst possible moment on the calendar. You are treating temporary market turbulence like a permanent catastrophe because panic makes every downward tick look like the complete destruction of your future.
Decades of steady compounding rely on a quiet, painfully boring mechanic that human biology resists at every turn. The financial markets reward absolute stillness through every storm, yet your nervous system treats falling portfolio numbers as an immediate physical threat demanding instant, visible action.
When you pull your money out during a routine correction, you sabotage thirty years of exponential growth simply to buy five minutes of fake psychological relief. The hidden price tag of that single panicked transaction shows up decades later as years of unnecessary labor you never needed to perform.
Close the browser app, walk away from the screen entirely, and let your automatic index fund contributions do what they were engineered to do without your frantic, counterproductive interference.
Market Volatility Response Plan
7. What Do People Misunderstand About Emergency Funds?
I used to treat my emergency fund as a hidden slush fund for concert tickets or a spontaneous weekend trip whenever a bonus hit my account. It felt harmless to raid the buffer for something fun, since I always planned to pay it back next month.
You view that cash reserve as extra spending money waiting for a good time, but treating it like discretionary funds completely misses its actual purpose. When an unexpected car repair or sudden medical bill arrives, you realize too late that the money was never meant for entertainment.
A true emergency fund acts as emotional insurance that protects you from making panicked career or financial choices during a crisis. Knowing you have three months of living expenses sitting untouched changes how you handle pressure from an employer or a sudden life disruption.
The next time you are tempted to pull from your reserve for a non-essential purchase, leave the money alone and use a separate credit card installment or smaller side savings for the treat instead. Keep your safety buffer sacred so it can keep your decisions calm.
💡 PRO TIP
Separate Your Accounts
Keep your emergency savings at a completely different bank so you are never tempted to raid it for non-emergencies.
8. Why Buying Cheap Goods Often Costs Twice as Much
The standard financial advice tells you to always hunt for the lowest possible price on every household item, tool, or piece of clothing to keep your monthly expenses as low as possible.
That strategy falls apart the third time a bargain shoe sole detaches during a rainy commute or a cheap kitchen appliance motor burns out completely after just fourteen months of light use.
Buying durable, well-made items upfront usually costs significantly less over a decade than repeatedly replacing flimsy substitutes every single year when they fail.
Shift your purchasing habit by looking specifically for reinforced stitching, solid wood construction, and repairable parts instead of reflexively chasing the steepest upfront discount.
9. What Does Financial Research Reveal About Spending and Joy?
I just wanted something nice that would make the living room look finished.
Researchers who study human behavior keep finding that experiential purchases outlast material goods in long-term satisfaction. Buying status symbols provides a temporary spike, but shared memories and quiet peace hold value for decades.
The next time you are deciding between a physical object and an outing with someone you care about, pick the experience and notice how long the memory stays with you.
10. How Can You Honestly Evaluate Your Relationship with Debt?
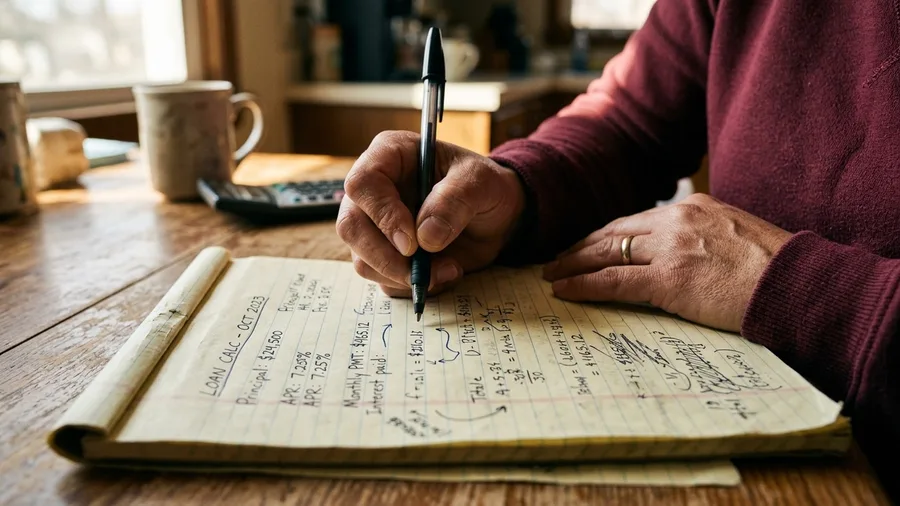
Ten seconds is all you need to answer this single question about your financial life. Do your monthly debt payments restrict your career choices or give you freedom?
If debt makes you stay at a miserable job because you need the next paycheck to service interest, that is a warning sign. Your obligations are choosing your office for you.
Look at your balance sheet tonight and label every credit line by how much freedom it actually took away. If the answer makes you uncomfortable, stop taking on new balances immediately and put every extra dollar toward clearing the highest interest first.
11. What Words Help You Say No to Impulse Purchases?
I used to think that resisting an impulse purchase required an ironclad willpower to simply stand in the aisle and conquer the craving on the spot.
You stand in a store aisle staring at an item you did not plan to buy, feeling the familiar pull of immediate gratification while trying to justify the purchase by telling yourself it is on sale and you deserve a treat after a long week.
What usually follows that internal debate is buyer remorse twenty-four hours later when the thrill wears off and the item sits unused on a shelf.
Instead, use a hard cooling rule by saying out loud, I will wait seventy-two hours, and if I still want it then, I can come back for it, before you put the item back on the shelf and walk out of the store.
12. When Is Spending Money on Convenience Actually Justified?
There are moments when spending money to buy back your time is a wise investment rather than lazy excess.
When work hours spike and your health suffers from exhaustion, paying for meal delivery or a reliable house cleaner protects your sanity.
Distinguish between mindless luxury and strategic time-buying, using cash only where it genuinely preserves your wellbeing.
13. Why Your Network Matters More Than Your Portfolio
People often assume that absolute financial independence means never needing anyone else to navigate life’s unexpected hurdles.
A heavy bank account provides financial insulation, but reliable human relationships act as the actual safety net when things break down. When a crisis hits, cash cannot drive you to the hospital, listen to your worst fears, or help you rebuild after a sudden loss.
Investing time in community and trustworthy friendships pays long-term dividends that no stock market index can ever replicate.
Building this network requires deliberate effort long before you actually find yourself in a tight spot. Make a list of people you trust completely, and commit to nurturing those connections regularly instead of treating them as a secondary priority.
Reach out to someone this week without needing a favor, treating that interaction as a core pillar of your overall security.
Connection is capital.
14. How Does Clear Financial Tracking Change Your Daily Stress?
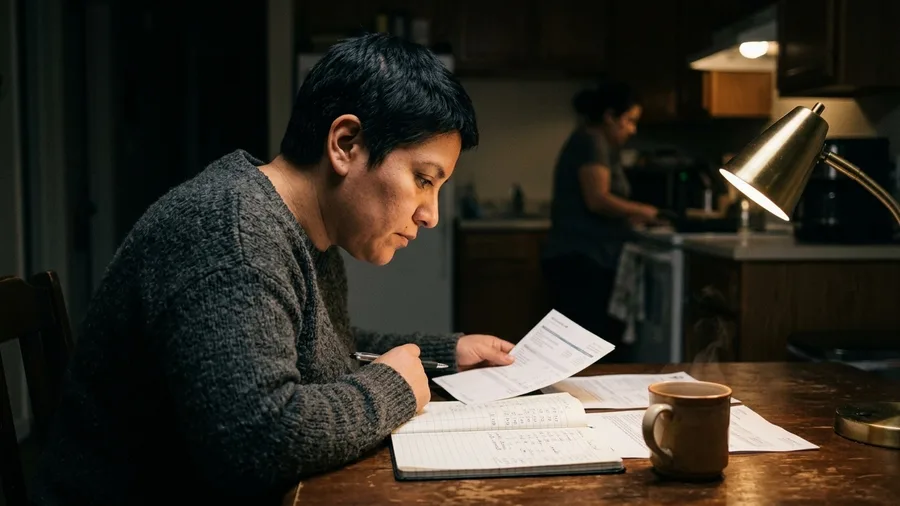
You sit down once a week with your bank statements, looking directly at every dollar that came in and went out. The kitchen table is quiet at seven on a Sunday morning, just the hum of the refrigerator and the growing stack of receipts spread out in front of you.
The unknown balance creates a quiet, persistent background panic.
It takes ten quiet minutes with a ledger and a cup of tea, replacing vague financial dread with absolute certainty about where you stand.
Pick your tracking day and protect it.
15. What Do Decades of Experience Teach You About Wealth?
What do decades of actual living teach you about what money is really for when the dust finally settles?
When you reach seventy, researchers who study long-term life satisfaction keep finding the same quiet truth.
You realize that money was never a scoreboard or a measure of personal worth.
The figures in your account are simply stored energy meant to give you choices, autonomy, and peace of mind when surprises happen.
People who chase status symbols discover too late that the things they bought owned them instead of the other way around.
True wealth is waking up in the morning without anxiety about who you have to impress or what emergency is waiting around the corner.
Build that quiet margin into your life starting today, and let the rest of the noise take care of itself.
What Thirty-Five Years Actually Teaches Us
You do not have to fix every single financial habit by tomorrow morning or overhaul your entire life in one weekend.
Pick one small adjustment from this list, let it settle into your routine for a month, and give yourself permission to take the long view.